


 Inglês (pdf)
 Artigo em XML
 Referências do artigo

 Tradução automática
 Enviar este artigo por email
 Citado por SciELO
 Similares em
SciELO

 Permalink


1. Introduction
Bolivia is currently undergoing significant macroeconomic distress, characterized by acute foreign exchange shortages, rising inflationary pressures, and a sharp decline in international reserves. The reduction of reserves from over $us15 billion in 2014 to just over $us2 billion by late 2024 has exacerbated fuel scarcity, elevated domestic prices, and fostered a thriving black market for U.S. dollars, where exchange rates often exceed twice the official rate. These developments have strained the country’s capacity to import essential goods and have intensified pressure on the long-standing fixed exchange rate of Bs6,96 per $us, in place since 2011.
In response to these pressures, the government has explored alternative arrangements, including trade agreements denominated in Chinese yuan, to reduce reliance on the dollar. Nevertheless, the persistent shortage of foreign currency continues to constrain the financial system and disrupt sectors dependent on international transactions. This economic fragility is compounded by rising political uncertainty, including internal divisions within the ruling party and an attempted coup in June 2024, further eroding public and investor confidence.
Against this backdrop, the demand for U.S. dollars as a store of value has intensified. Since early 2023, financial intermediaries and exchange houses have faced overwhelming demand for foreign currency, frequently resulting in rationing and long queues. The Central Bank of Bolivia (BCB) has stepped in as a key supplier of foreign currency to stabilize expectations, but ongoing structural and institutional weaknesses have undermined these efforts.
This pattern reflects a broader historical dynamic in which inflation and exchange rate crises co-occur. As documented by Reinhart [1], nominal depreciation and inflation are strongly correlated in emerging economies. Figure 1 illustrates this relationship for selected countries in Latin America, including Bolivia, where episodes of inflation are systematically accompanied by nominal depreciation, reinforcing incentives for dollarization. In these contexts, local currency loses value while the U.S. dollar remains stable, encouraging households and firms to increase their foreign currency holdings.
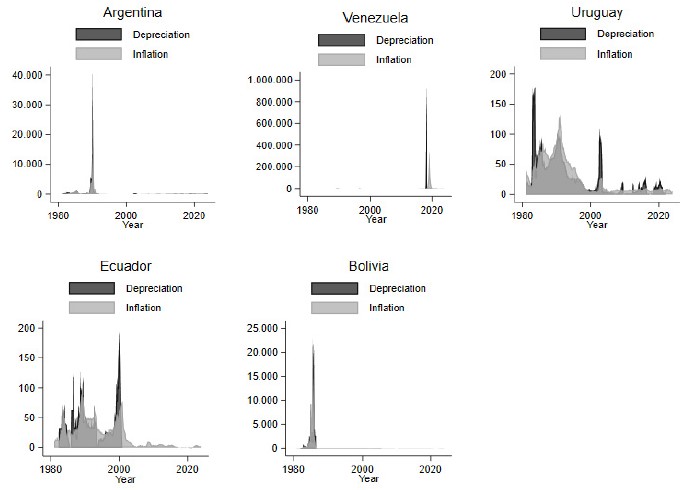
Source: CEPAL, Central Banks.
Figure 1: Nominal Depreciation and inflation rates in selected economies (%)
The Bolivian case is further complicated by a structural decline in foreign exchange inflows. Since 2023, both exports and remittances (the main sources of external currency) have contracted significantly. At the same time, domestic financial institutions have been unable to generate new foreign currency flows, instead recycling existing reserves to meet demand.
Figure 2 illustrates the resulting foreign exchange gap, which has contributed to the emergence of a parallel market and intensified speculative behavior. This analysis provides complementary empirical evidence of this divergence between the official exchange rate and the effective market valuation of U.S. dollars in Bolivia, proxied by the USDT (Tether) price in the informal cryptocurrency market. Utilizing Bollinger Bands and exponential moving averages (EMAs), the figure captures a persistent and increasingly volatile deviation of the selling price from its historical mean, particularly from late 2024 to early 2025. These dynamics underscore growing pressures in the informal market and highlight the widening gap between official policy and market expectations. The sharp increases observed in March 2025 reflect speculative stress and acute dollar scarcity, reinforcing the hypothesis that foreign currency is being demanded as a store of value amid mounting macroeconomic instability. This behavior offers a real-time signal of accelerating dollarization and further motivates the need to investigate the structural determinants of dollar demand under conditions of macro-financial fragility.
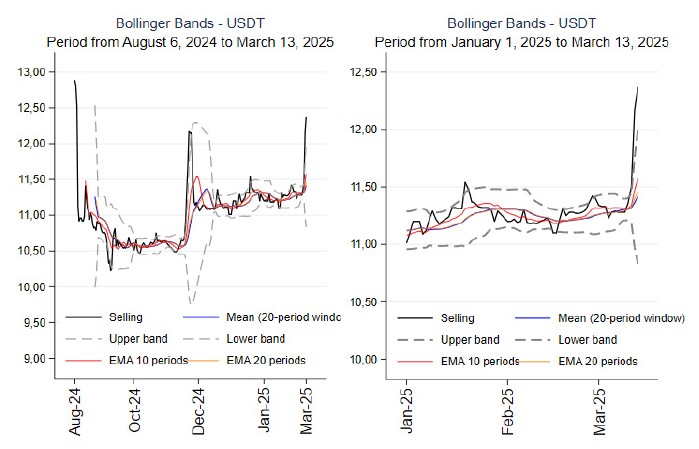
Source: Own elaboration.
Note: Parallel exchange rate for sales pertains to the average price of USDT in the free cryptocurrency market.
Figure 2: Exchange Rate Discrepancy: USDT vs. Bolivianos
These stylized facts reflect a growing perception of economic risk, prompting agents to rebalance their portfolios toward foreign assets. The underlying mechanism is represented in Figure 3, which shows that dollar availability in Bolivia depends primarily on external flows (exports and remittances) and internal recycling by financial intermediaries. As these channels weaken, the scarcity of dollars intensifies, reinforcing demand for foreign currency and weakening the effectiveness of monetary policy.
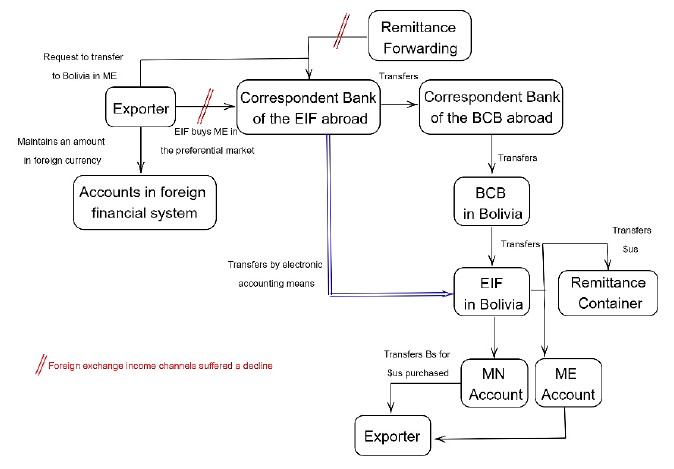
Source: Own elaboration.
Note: (MN) Domestic Currency; (ME) Foreign Currency; (BCB) Central Bank; (EIF) Financial Intermediation Entities.
Figure 3: Foreign Exchange Scheme for obtaining foreign currency
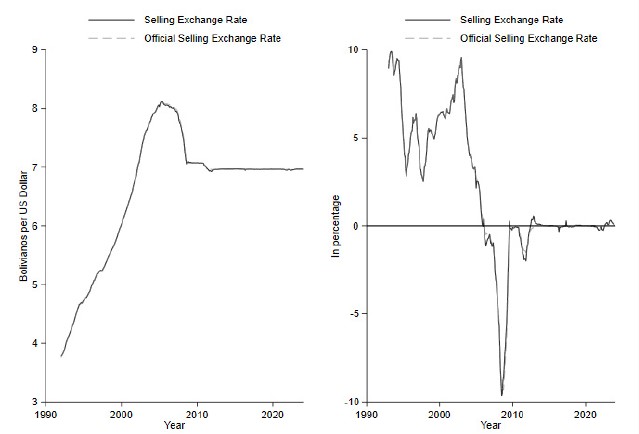
Behavioral indicators also signal a loss of confidence in local currency. After years of expansion, monetary aggregates such as M1 and M2 have recently stagnated or declined in real terms (Figure 4), suggesting a shift in preferences away from bolivianos. Real interest rates have become more volatile, while inflation have risen sharply. The fixed exchange rate regime has prevented a nominal depreciation that could restore equilibrium, leading instead to mounting imbalances (Figure 5).
The persistent erosion of Bolivia’s international reserves has significantly constrained the Central Bank’s capacity to uphold the fixed exchange rate regime. In an effort to maintain the peg, the Central Bank has resorted to selling foreign currency, further diminishing its reserves. This strategy, while temporarily stabilizing the official exchange rate, has inadvertently intensified the scarcity of U.S. dollars in the formal market, leading to the emergence of a parallel exchange rate that diverges markedly from the official rate. The increasing gap between official and unofficial exchange rates has eroded public confidence in the national currency, prompting economic agents to increasingly seek refuge in the U.S. dollar as a more stable store of value. This shift in preference has accelerated the process of dollarization within the economy, complicating the effectiveness of domestic monetary policy and exacerbating the obstacles associated with managing liquidity and controlling inflationary pressures.
This paper investigates the structural determinants of dollar demand in Bolivia under these conditions of macro-financial fragility. The research question centers on how inflation, real interest rates, devaluation expectations, and perceived uncertainty shape the demand for dollars as a store of value. While the literature on money demand in Bolivia has addressed issues such as bolivianization, financial deepening, and de-dollarization, it has not incorporated the effects of recent shocks, including the Covid-19 aftermath, declining reserves, and political volatility.
To address these gaps, we estimate a foreign currency demand function using monthly data from December 1993 to September 2023. The methodology is based on the Autoregressive Distributed Lag (ARDL) framework, which captures both short and long-term dynamics. Our model incorporates inflation, real interest rates, economic activity, and devaluation expectations as explanatory variables. In addition to baseline estimates, we conduct counterfactual simulations and structural impulse response analysis to evaluate the response of dollar demand to exogenous shocks.
Our findings confirm that macroeconomic uncertainty, particularly expectations of depreciation, drives precautionary accumulation of foreign currency balances. This behavior is consistent with theoretical and empirical frameworks, in which inflation and volatility reduce the attractiveness of domestic money. The results highlight the fragility of the current monetary regime and underscore the need for credible and coordinated policies to restore confidence in the boliviano.
In line with these concerns, this document examines the structural determinants of U.S. dollar demand in Bolivia from a store-of-value perspective, particularly under conditions of macroeconomic uncertainty. Employing an Autoregressive Distributed Lag (ARDL) model, it explores the long- and short-run effects of inflation, real interest rates, economic activity, and devaluation expectations. The central hypothesis is that heightened uncertainty (especially rising inflation and anticipated depreciation) diminishes confidence in domestic currency, encouraging a precautionary shift toward foreign currency holdings. This behavior reinforces dollarization dynamics. The expected findings align with theoretical predictions, indicating negative effects of inflation and devaluation expectations, and a positive income effect on dollar demand.
The rest of the paper is structured as follows: in Section 2, which develops a literature review of the problem at hand, highlighting evidence in the Latin American Region and Bolivian studies. Section 3 reviews sources of information. Section 4 outlines the theoretical and econometric methodology used to estimate the dollar demand. Section 5 presents the estimation results for the Bolivian case, and finally, Section 6 establishes the conclusions and policy recommendations.
2. Literature Review
Among the main theories for estimating demand, the quantity theory stands out, developed by Fisher and Pigou, which suggests that the demand for money is motivated by its role as a transactional medium, being directly proportional only to income. Keynes added two additional motives to this theory: the speculative motive and the precautionary motive, which are synthesized in the IS-LM model formalized by Hicks. This suggests that such demand depends inversely on income and interest rates. Following Keynesian theory, the interest rate was recognized as a fundamental variable in monetary theory.
More sophisticated theories have attempted to explain the determinants of money demand by incorporating the principle of rationality of economic agents. The inventory models of Baumol and Tobin, Tobin’s portfolio allocation, Friedman’s monetarist theory, Sidrauski’s Money in the Utility Function (MIU) model, and Clower’s Cash in Advance model are key references in this regard. In most of these theories, it is assumed that economic agents (households and families) maintain money inventories in the same way that businesses maintain inventories of goods. Additionally, the number of transactions, transaction costs, income, and interest rates are identified as the main determinants of cash demand. For economies experiencing hyperinflation, Cagan’s money demand model is frequently used, indicating that higher inflation leads to a lower willingness among the public to hold currency; as money loses its value, the public will seek to dispose of it as quickly as possible by acquiring goods or services. Lastly, an unexplored topic for the country is McKinnon’s money demand model for under-developed economies, which posits the hypothesis of complementarity between money and physical capital.
These theories have been used to empirically calculate money demand in various countries. We continue by reviewing those in which they were implemented to estimate the demand for dollars or foreign currency in their economies, identifying their estimation methodology, analysis period, and main findings.
2.1. International contributions
Calvo and Végh [2] delve into the broader implications of currency substitution for developing economies. Their work identifies dollarization as a gradual process that starts with foreign currencies serving as a store of value before becoming a medium of exchange in inflationary environments. They argue that the persistence of currency substitution even after disinflation is a challenge for policymakers, as it reduces monetary independence and complicates stabilization efforts. Their analysis underscores the importance of addressing fiscal imbalances to regain confidence in domestic currencies.
Regarding the methodology used in the present investigation, the initial precursors were Kamin and Ericsson [3], who tried to explain the dollarization process that Argentina underwent in the early 1990s by modeling the demand for both domestic and foreign currency as a response to macroeconomic instability. Using a cointegration approach, they show that inflation, interest rate differentials, and exchange rate expectations significantly influence the shift toward foreign currency, primarily as a store of value. Notably, they revealed a negative “ratchet” effect of inflation on the demand for pesos, whereby past inflation shocks permanently reduced trust in the domestic currency. Their findings underscore that dollarization persists even after stabilization efforts, reflecting a deep-seated loss of confidence in domestic monetary institutions. This highlights the importance of value preservation motives in understanding foreign currency demand, a perspective central to this paper.
Agénor and Khan [4] provide a comprehensive analysis of currency substitution in ten developing countries, emphasizing the role of forward-looking rational expectations. They identify the foreign interest rate and expected depreciation of the parallel market exchange rate as critical factors influencing the relative demand for foreign currency. Their findings reveal that in the absence of credible monetary policies and financial stability, currency substitution becomes a pervasive response, reflecting both precautionary and speculative motives for holding foreign assets.
Following this, Jijón [5] analyzes the Ecuadorian economy prior to the dollarization scheme implemented in 2000. The main result indicates that the foreign currency in circulation would represent 70% of the national currency in circulation, amounted to approximately $us358 million for the period analyzed of 1998. Similarly, Orellana [6] estimates that the percentage of foreign currency in circulation fluctuated between 60% and 80% for Bolivia during the period 1994 to 1998.
Rodríguez Merlo [7] covers a sample spanning from 1980 to 2008, using M1 and M2 monetary aggregates as the dependent variable. Among the results, the importance of the effect of currency substitution in Uruguay and its implications for the country’s economic policy is highlighted, as well as the need to monitor and pay attention to it. In particular, the elasticities of inflation and interest rates within money demand were -0.170 and -0.016 on average, respectively.
Valev [8] examines the hysteresis effect of currency substitution, particularly its entrenchment despite successful inflation stabilization. Drawing on survey data from Bulgaria, the study highlights the significant role of network externalities, where the widespread use of foreign currency becomes self-reinforcing. Additionally, the perception of ongoing risks of domestic currency depreciation perpetuates dollarization, particularly in rural areas with limited access to financial services. These findings align with earlier studies by Calvo and Végh [2], emphasizing that historical instability leaves long-lasting imprints on currency preferences.
The work of Harun et al. [9] adds further depth to the analysis of money demand in emerging economies by employing a Panel ARDL approach. Their findings highlight that real income and real interest rates significantly influence money demand in the long run, while short-term relationships with interest rates are less significant. These results suggest that fiscal policies are more effective than monetary policies for stabilizing emerging economies, a point that resonates with the dynamics of foreign currency demand in partially dollarized economies.
Cadenas [10] utilizes Kamin and Ericcson’s methodology, adapted for the case of Venezuela, an economy with hyperinflation expectations. This involves estimating an expanded money demand function with a variable to capture the “ratchet” or hysteresis effect of dollarization. Once the coefficient of the ratchet variable is obtained, it is used to reconstruct estimates of the amount of dollars circulating in the economy as a medium of exchange. Table 1 and 2 summarizes the quantitative findings of the studies; generally, the techniques applied to this topic correspond to ordinary least squares regressions, maximum likelihood, and cointegration techniques, the latter presuming a long-term relationship among the variables used. Furthermore, this methodology is useful and applicable in partial dollarization schemes, known as currency co-circulation, and in schemes prior to total dollarization, as occurred in Ecuador.
Park and Son [11] using panel data from 28 countries between 1995 and 2016, find that high inflation, real currency depreciation, and institutional weakness are key drivers of rising dollarization. Their results highlight that in dollarized economies, inflation has a stronger and more persistent effect on foreign currency use, suggesting a structural shift in currency preferences under prolonged macroeconomic instability. Complementing this, Garcia-Escribano and Sosa [12] examine financial de-dollarization in Bolivia, Peru, Uruguay, and Paraguay, and identify inflation shocks and exchange rate volatility as major contributors to initial dollarization. They show that successful de-dollarization is closely tied to macroeconomic stabilization, real currency appreciation, and targeted regulatory measures. Both studies highlighted that when inflation undermines confidence in the local currency, households and firms turn to foreign currency, initially as a safeguard for savings, and later for transactions. A mechanism we account for explicitly by incorporating inflation as an important variable in our model. Their findings reinforce the importance of modeling asymmetries in the determinants of money demand. In line with their approach, our study also employs ARDL techniques.
2.2. National contributions
Among the main contributions to national empirical evidence, Arce [13] stands out, which, through error correction models for the short and long term, demonstrates that in the long term, economic agents demand money for both transactional purposes and as a financial asset. It also provides evidence that the depreciation rate of the boliviano is the most important factor measuring the opportunity cost of holding national currency, a fact attributed to the inflationary memory of economic agents and their need to preserve the purchasing power of their resources. However, in the short term, the demand for money is primarily for transactional purposes and is related to the growth rate of the product. The variables used include monetary aggregates, GDP, the devaluation rate, and interest rates in both national (MN) and foreign (ME) currencies.
Mendoza et al. [14] emphasize the importance of expectations about the evolution of the exchange rate in the demand for foreign currency in Bolivia, as it reflects relative preference. They concluded that during periods of uncertainty, as reflected in exchange rate movements, there is an increase in the public’s cash holdings in dollars.
Partially, Chalup and Jurado [15] base their analysis on identifying the best scale variable that could explain the demand for money, using real consumption as a proxy variable for the first time. They concluded that GDP is the scale variable that best explains money demand and that devaluation expectations do not have a statistically significant influence on money demand.
On the other hand, Cerezo and Ticona [16] investigate the relationship between money demand and seigniorage in Bolivia, incorporating financial bolivianization, which has been experienced in Bolivia mainly since 2006, as a proxy for preference for the national currency. They additionally found that variables such as income, interest rates, and expected inflation have contributed to the increase in money demand both in the short- term and in the long term.
Finally, Barrenechea and Gómez [17] expand the analysis of money demand by incorporating variables such as financial innovation or uncertainty indices, concluding that there is a significant positive effect on money demand. These aspects will not be addressed in this document, although they are left for the reader’s interest to explore. Regarding the model used, the study employs an ARDL model to estimate the relationship between uncertainty and money demand in Bolivia. This type of model is useful for analyzing both long- and short-term relationships among variables, allowing for the capture of both short-term adjustment dynamics and long-term equilibrium relationships.
Table 1: Latin American Dollar Demand Estimates (Part 1)
| Author | Period | Country | Method | Dependent Variable |
|---|---|---|---|---|
| Mendoza, Laguna, Rodriguez | 1991-2009 | Bolivia | Maximum Likelihood | M1 |
| Jijón | 1982-1998 | Ecuador | M1 | |
| Orellana | 1987-1998 | Bolivia | M1 | |
| Kamin, Ericcson | Argentina | Cointegration | M3 | |
| Rodríguez Merlo | 1980-2008 | Uruguay | Linear Regression | M1, M2 |
| Cárdenas | 2017-2021 | Venezuela | Cointegration | M2 |
| Arce | 1990-2002 | Bolivia | VECMCE | M1 to M3 |
| Chalup, Jurado | 1995-2013 | Bolivia | Linear Regression | M2 |
| Cerezo, Ticona | 2001-2015 | Bolivia | Linear Regression | Issuance |
| Mora, Heredia, Zeballos | 2001-2020 | Bolivia | ARDL | Issuance M2 |
Source: Based on the literature review section.
The summary table highlights other aspects to be reviewed and considered in the model development, such as:
Homogeneity in terms of the variables used for estimations, particularly regarding their determinants associated with conventional theories. Thus, the demand for money is approached using measures of monetary aggregates, especially M1, M2, and broader aggregates like M3.
The estimates presented in these documents cover different time horizons, making strict comparisons difficult, although they can provide insights into the sign and magnitude of the studied variables.
The estimation methods used, primarily related to maximum likelihood models, linear regression, and co-integration.
For the Bolivian case, it is evident that there is variability in the results even when the same estimation method is used, suggesting that the analyzed period has a significant influence on the obtained results.
The body of previous studies on money demand in Bolivia is limited. Research has adopted an empirical approach and focused on econometrically investigating the existence of long-term relationships for real balances and analyzing the stability of that function. None of these works considered analyzing the specification used by Kamin Ericcson’s.
Table 2: Latin American Dollar Demand Estimates (Part 2)
| Author | Income | Interest Rate | Depreciation | Inflation | Ratchet-Inflation |
|---|---|---|---|---|---|
| Mendoza, Laguna, Rodriguez | -7,43 | -0,29 | -0,12 | ||
| Jijón | 0,75 | 0,78 | -0,09 | ||
| Orellana | 1,41 | -0,95 | |||
| Kamin, Ericcson | |||||
| Rodríguez Merlo | -0,016 | 0,062 | -0,050 | -0,057 | |
| Cárdenas | |||||
| Arce | 2,642 | 0,046 | -15,299 | ||
| Chalup, Jurado | 0,935 | -0,010 | -0,118 | ||
| Cerezo, Ticona | 4,390 | -0,168 | |||
| Mora, Heredia, Zeballos | 0,800 | 0,000 |
Source: Based on the literature review section.
3. Data
This section presents and describes the variables used to estimate the demand for U.S. dollars in Bolivia from a store-of-value perspective. The analysis relies on monthly time series data covering the period from December 1993 to September 2023, sourced from official institutions such as the Central Bank of Bolivia (BCB), the National Institute of Statistics (INE), and the Social and Economic Policy Analysis Unit (UDAPE).
The selected variables include outcome and explanatory indicators commonly used in monetary demand models, such as monetary aggregates, interest rates, inflation, economic activity, exchange rate indicators, and devaluation expectations. These variables were selected based on a comprehensive review of the literature and draw upon previous empirical studies focused on dollarization and currency demand in Latin American economies, as discussed in Section 2. This ensures that the model specification is both theoretically grounded and regionally relevant. The variables were chosen to capture the fundamental macroeconomic forces that influence agents’ portfolio allocation decisions, particularly in environments characterized by financial uncertainty and external imbalances. The detailed construction and evolution of each variable are presented in the following subsections.
3.1. Monetary Aggregates M1 and M2:
The variable under analysis has two definitions to identify which variable to use in the document.
M1: Monetary aggregate that includes currency and coins held by the public, including demand deposits in the national currency. This is money that can be used directly for transactions.
M2: Monetary aggregate that includes M1, as well as savings deposits in the national currency (MN) and inflation-indexed units (UFV). This indicator is more comprehensive than M1 as it includes other more liquid sources (Figure 4).
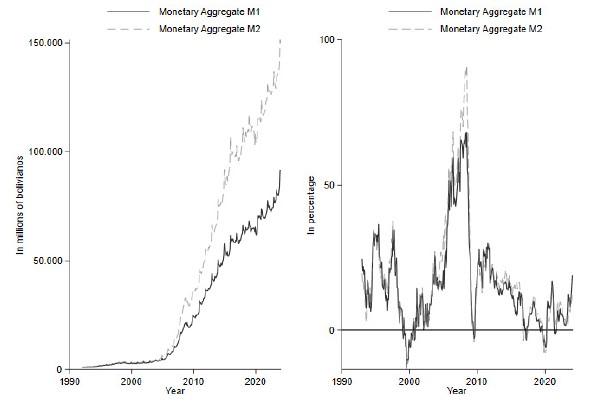
These monetary aggregates are used to monitor the amount of money in circulation, and their analysis can provide useful information about liquidity and the availability of money in a particular economy. In this case, it is observed that these variables have grown significantly since the end of 2005. Initially, this is identified as a greater preference of the public for the national currency (MN) over foreign currency (ME). Observing the substantial year-on-year growth rates recorded in subsequent periods, this preference gradually decreased due to external factors (international financial crises), political factors (elections), and even speculative factors (rumors about the performance of the financial system)1.
3.2. Real Passive Interest Rate
The return on financial assets was taken as the opportunity cost of money. In this model, the average interest rate of the banking system was used for both savings accounts and fixed- term deposits (DPF) in the national currency (MN), with data collected from UDAPE. The high levels of interest rates in MN at the end of the 1990s are mostly explained by credibility issues toward financial entities due to market exit processes, either through forced sales (absorptions) or mergers, which could have caused changes in the competitive structure of the market. Consequently, in 1999, high interest rates for DPF in MN were recorded, around 10%, in an attempt to encourage the population to deposit their savings in Financial Intermediation Entities (EIF). After this period, the real return on deposits was observed to decrease, even becoming negative or close to zero.
3.3. Consumer Price Index
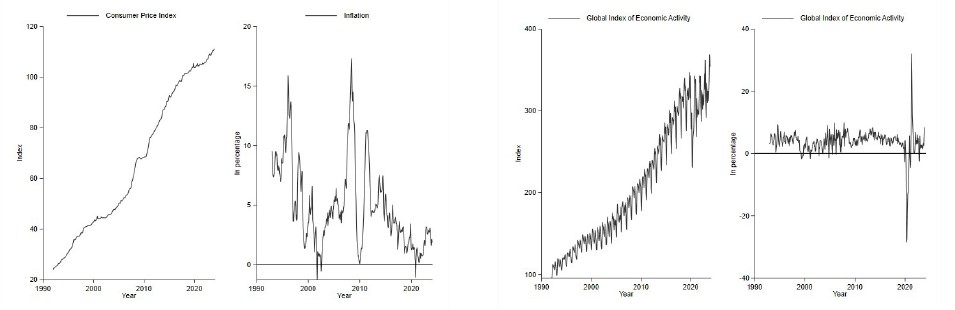
This index is crucial to evaluating inflation and the cost of living in the country. During the 1990s, Bolivia experienced high and volatile inflation due to economic liberalization and market opening. In the early 2000s, more stable and disciplined economic policies were implemented with a focus on controlling inflation. In the last decade, the CPI in Bolivia has been carefully managed through various economic and fiscal policies.
Despite some episodes of inflationary pressure, the CPI has shown a relatively stable trend, allowing the purchasing power of consumers to be maintained (Figure 6).
3.4. Exchange Rate
The exchange rate reflects the value at which the national currency can be sold against foreign currency. During the 1990s, Bolivia underwent a series of economic reforms that included the liberalization of the exchange rate. During this period, the selling exchange rate experienced significant devaluation moments. In the early 2000s, the Central Bank of Bolivia (BCB) adopted a managed exchange rate policy, allowing some flexibility but within a controlled framework. In the last decade, the exchange rate in Bolivia has been mostly pegged to the US dollar. This “pegging” policy has been implemented to provide economic stability, attract foreign investment, and protect the purchasing power of the population. However, this strategy has also led to challenges, such as the need to maintain sufficient international reserves to sustain the fixed exchange rate and the difficulty of adjusting monetary policy in response to external shocks (Figure 5).
3.5. Global Economic Activity Index (IGAE)
As a monthly proxy indicator of GDP, the relationship indicated by the literature suggests it is positive, given that an increase in local economic activity would result in a growth in the demand for money in the national currency (MN) associated with greater internal demand dynamics, whether for consumption, investment, or spending. This implies that there is a greater demand for money in MN, which can be redirected to the acquisition of foreign currency (ME), especially in times of uncertainty. The year-on-year growth graph shows that the IGAE experienced positive growth for at least 20 years, influenced by the boom in oil and mineral prices Peñaloza and Valdivia [18]. However, more notably, its most significant declines were recorded during the Asian crisis, the political crisis at the end of 2019, and the COVID-19 pandemic (Figure 6).
3.6. Devaluation Expectations
Following the methodologies of Ize [19], Aguilar and Dib [20], and Kamin and Ericsson [3], the construction of the ratchet variable was carried out, considering the real exchange rate. The indicator aligns with the beginning of the bolivianization process and the expectations generated by the international financial crisis of 2008. As a result, the countries in the region experienced depreciations of their currencies, and in the case of Bolivia, these movements translated into devaluation expectations. Furthermore, a greater-than-zero expectation is observed throughout almost the entire analysis period, indicating the economic agents’ forecast regarding the behavior of this variable (Figure 7).
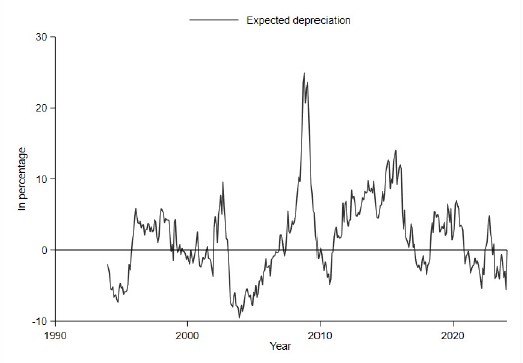
Note: It was defined as the percentage discrepancy between the twenty-four-month moving average of the real exchange rate index and the effectively observed real exchange rate. Furthermore, to continue with the proposal by Kamin and Ericsson [3], the maximum value of the proposed methodology is taken. Thus, the variable is constructed as follows:
Where is the real exchange rate variable. Thus, the devaluation expectations variable would be positive when the real exchange rate index observed in a given month is lower than its moving average, while this variable will be negative (i.e., a nominal appreciation of the exchange rate is anticipated) during periods when the real exchange rate level is higher than its twenty-four- month moving average.
4. Methodology
The ARDL model was introduced by Pesaran et al. [21] to incorporate I(0) and I(1) variables in the same estimation. If the variables are I(0) stationary, then Ordinary Least Squares (OLS) is appropriate. However, if all variables are I(1) non-stationary, it is advisable to use a Vector Error Correction Model (VECM) (Johansen approach), as it is a much simpler model.
We cannot estimate conventional OLS on the variables if any or all of them are I(1) because these variables will not behave as constants, which is required in OLS. Since most of them change over time, OLS will erroneously show high t-values and significant results, but this would actually be inflated due to the common time component; in econometrics, these are referred to as spurious results, where the R-squared of the model becomes higher than the Durbin-Watson statistic. Therefore, we move on to a new set of models that can work with I(1) variables.
4.1. Theoretical model
The demand for money is a central concept in monetary theory, as it helps to understand how economic agents decide the amount of real money balances to hold based on key macroeconomic variables such as income, prices, and opportunity costs represented by interest rates.
This framework is rooted in the quantity theory of money, which establishes a fundamental relationship between the nominal quantity of money, the general price level, real income, and the velocity of money. The relationship is expressed as:
where M represents the nominal quantity of money, P is the general price level, Y is real income, and v is the velocity of money, which measures how often a unit of money circulates in the economy over a given period.
Traditionally, v was assumed to be constant, but Cagan [22] argued that it may vary with the interest rate (r). Higher interest rates, which act as opportunity costs for holding money, incentivize agents to reduce real money balances in favor of higher-yielding financial assets. Consequently, the velocity of money increases. This relationship is formalized as:
Incorporating this dependency into the demand for real money balances yields:
where the demand for real money balances decreases with higher interest rates, reflecting the rising opportunity cost.
Logarithmic Model
The logarithmic specification of the model, suitable for econometric estimation and interpretation, is:
In this framework, the growth rate of real income (Δln (Yt)) reflects economic activity, while inflation (πt) and the interest rate (rt) represent opportunity costs that negatively influence the demand for real money balances.
Growth Rate Model
To analyze the dynamic behavior of real money demand, the model can be expressed in terms of growth rates:
In this framework, the growth rate of real income reflects economic activity, while inflation and the interest rate represent opportunity costs that negatively influence the demand for real money balances.
4.2. Econometric approach
ARDL models are standard regressions that include lags of both the dependent and explanatory variables as regressors as indicated in Sarkodie and Owusu [23]. The typical nomenclature for these models follows AKDL(p,q1,...,qk), where p is the number of lags of the dependent variable, q1 is the number of lags of the first explanatory variable, and qk is the number of lags of the k-th explanatory variable in the model, specifically it could be denoted as follows.
This document proposes and utilizes the money demand method of Kamin and Ericsson [3], applying equation 1 to the proposed study variables.
Where Mt represents the nominal money approximated by the monetary aggregate M1 or M2 in contemporary terms. rt is the real passive interest rate2, used as a proxy for the opportunity cost of holding monetary balances (deposits) in the financial system. Pt is the Consumer Price Index, utilized to deflate the variables and obtain them in real terms. Additionally, ln(Pt) - ln(Pt-4), represents the year-on-year inflation rate. PIBt it is the indicator of the scale variable, ln(PIBt) - ln(PIBt-4) it is the year- on-year growth rate. E refers to the preferred selling exchange rate. Furthermore, ln(Et) - ln(Et-4) it is the year-on-year devaluation rate. Finally, ln(Pt) - ln(P0) captures the maximum inflation expectations, calculated as the maximum inflation over a 24-month period.
The authors consider that while ln(Pt) - ln(P0), in accordance with the framework presented by Kamin and Ericsson [3], captures the inflation expectations formed by economic agents, there is a prior phase identified by the stylized facts presented (Figure 1), which are the exchange rate speculations. Additionally, the estimation will be conducted using monthly frequency data, thus the IGAE (Gross Domestic Product Indicator) is used as the scale variable. With this in mind, a modification is proposed to capture this phenomenon in the Bolivian economy. Another advantage of this econometric methodology is that it allows for the incorporation of dynamic effects to explain the behavior of money demand and to examine the long- term cointegration relationship among the variables, following Pesaran, Shin, et al. [24] and Strøm [25]. This feature of the model is leveraged to estimate the equation in both the short and long term through the following expanded specification.
The model generally presents an intercept, lags of the dependent variable, and lags of the explanatory variables. Specifically, δ0, γ0, ϕ0, λ0, ρ0 measure the contemporaneous effect of the explanatory variables on the real monetary balances. Regarding the selection of the number of lags, standard information criteria such as Akaike, Schwarz, or Hannan-Quinn are taken into account. To execute the ARDL model, certain preliminary conditions must be verified:
The dependent variable should not be stationary for the model to perform better.
None of the variables should be I(2) under normal conditions (ADF test).
None of the variables should be I(2) in the presence of structural breaks (Zivot-Andrews test).
Given the estimation of Equation (3), which captures the dynamic relationship between real monetary balances and interest rates, inflation, growth, devaluation, and their expectations, it is possible to transform the model into a long-term representation of the dependent variable in response to changes in the explanatory variables. The calculation would be given by the following expressions in (4).
It is expected that the coefficient of the interest rate θ0, will be negative, as it represents the opportunity cost of holding money as deposits. Similarly, the coefficients θ1 and θ3 are also expected to be negative because goods (inflation) and dollars (exchange rate) are considered substitutes for money. On the other hand, θ2 could be positive, as a higher level of output translates into greater demand for money. Finally, θ4 captures the expectations of devaluation and should be negative, indicating the behavior and memory of economic agents in response to past devaluations.
While the ARDL approach is suitable for variables with different orders of integration and allows a clear distinction between short-run dynamics and long-run relationships, its use does not, by itself, rule out potential endogeneity between the regressors and foreign-currency demand. In the Bolivian context, at least three plausible sources of bias can be identified: (i) simultaneity between dollar demand and depreciation expectations (agents dollarize because they anticipate a devaluation, but exchange-market tensions can in turn reinforce those expectations) and (ii) feedback mechanisms between economic activity or the real interest rate and dollarization (portfolio shifts toward foreign currency can affect liquidity and credit and, through that channel, influence the very variables included in the model) that may induce correlation between the error term and policy or expectations variables.
Including lags and using an error-correction representation substantially mitigates contemporaneous simultaneity and helps isolate the long-run relationship. However, in an environment with recurrent exchange-rate episodes such as Bolivia’s, it is reasonable to acknowledge that some residual dependence between expectations and Foreign Currency demand may persist. Accordingly, the results should be interpreted as empirical evidence consistent with portfolio-substitution theory, rather than as strict structural identification.
Once the proposed econometric methodologies have been presented, we proceed with the estimation of the models. First, we will identify the statistical moments of the series studied.
Table 3: Statistics Summary Of Selected Variables
| Variable | Obs. | Mean | Median | MR | DAM | D.S | Min | Max | Range | A | C | Std. Error | Prob J-B |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Real M1 Balance | 358 | 328,3 | 295,1 | 316,4 | 340,0 | 250,5 | 45,2 | 753,8 | 708,6 | 0,2 | -1,6 | 13,2 | 0,0 |
| Real M2 Balance | 358 | 514,9 | 452,8 | 489,0 | 564,0 | 433,4 | 48,0 | 1.258,0 | 1.210,0 | 0,3 | -1,6 | 22,9 | 0,0 |
| Real Passive Interest Rate | 358 | 0,9 | 0,4 | 1,0 | 5,7 | 4,7 | -9,2 | 10,8 | 20,0 | 0,0 | -0,9 | 0,3 | 0,0 |
| Global Economic Activity Index | 358 | 211,5 | 197,3 | 208,1 | 84,0 | 71,0 | 105,1 | 362,1 | 257,0 | 0,4 | -1,3 | 3,8 | 0,0 |
| Consumer Price Index | 358 | 68,3 | 67,6 | 68,0 | 36,4 | 26,4 | 28,1 | 110,5 | 82,4 | 0,2 | -1,5 | 1,4 | 0,0 |
| Official Selling Exchange Rate | 358 | 6,8 | 7,0 | 6,8 | 0,2 | 0,9 | 4,5 | 8,1 | 3,7 | -0,9 | 0,1 | 0,1 | 0,0 |
| Devaluation Expectations | 358 | 1,7 | 1,5 | 1,4 | 5,1 | 5,6 | -9,6 | 24,9 | 34,5 | 0,9 | 1,9 | 0,3 | 0,0 |
Notes: MR: Robust mean, MAD: Absolute deviation from the mean, SD: Standard deviation, A: Asymmetry, C: Kurtosis, ee: Standard error of the mean, J-B: Jarque Bera.
Source: Own elaboration.
According to Table 3, the following can be highlighted: three measures of central tendency are presented: mean, median, and robust mean3. The highest standard deviation and range correspond to the variable m2r followed by m1r. For the case of the variables m1r , m2r, rpas, igae, ipc, emax there is a positive skewness, indicating a greater number of observations above the mean. In contrast, tc, reflects negative skewness. The kurtosis of the variables is platykurtic, except for the variable tc, emax, which shows very little concentration of data around the mean, presenting a very flat shape in all cases. Finally, according to the Jarque-Bera test, none of the variables exhibit a normal distribution, making it advisable to use transformations, such as logarithms, on the selected variables.
First, the order of lags is verified to determine which will be used in the stationarity tests for each variable included in the model. The selection of lags is carried out for both the level variables and the year-on-year growth rates (Table 4).
Table 4: Selection Of Optimal Lags
| Variable | Lag (Levels) | Lag (Y-o-y Rate) | Information Criterion Used |
|---|---|---|---|
| Real M1 Balance | 1 | Bayesian Information Criterion (SBIC) | |
| Real M2 Balance | 2 | Bayesian Information Criterion (SBIC) | |
| Real Passive Interest Rate | 3 | Bayesian Information Criterion (SBIC) | |
| Global Economic Activity Index | 4 | 2 | Bayesian Information Criterion (SBIC) |
| Consumer Price Index | 2 | 2 | Bayesian Information Criterion (SBIC) |
| Official Selling Exchange Rate | 4 | 4 | Bayesian Information Criterion (SBIC) |
| Devaluation Expectations | 1 | Bayesian Information Criterion (SBIC) |
Source: Own Elaboration.
Once the variables to be included in the model were defined, we proceeded to verify, as a preliminary step to estimating an ARDL model, that the unit root tests ensure that no variable I(2) is or higher, following Philips [26]. These tests were conducted using monthly data (in accordance with the available information) covering the period from 1993 to 2023. Initially, unit-root tests were performed to identify the order of integration of the variables used. For this purpose, the ADF unit root tests of Dickey and Fuller, (1981)4 were used to obtain more robust results. The variables were found to be stationary in the first differences, I(0). Furthermore, the stationarity of the variables expressed in year-on-year growth rates was evaluated, and it was found that these are also stationary (Table 5).
The next step is to determine whether the variables are sensitive to structural breaks. This involves checking for unit roots using the Zivot-Andrews test, which allows for structural breaks. If a variable is found to be I(2), then there is an issue that needs to be addressed, such as adding a structural break variable to the model or removing the break from the variable. The test is checked and interpreted the same way as the ADF test. Additionally, this test provides information about the structural break of the dependent variable, which can be incorporated into the model5 (Table 5). Once verified that none of the variables are I(2), we can proceed to estimate the ARDL model.
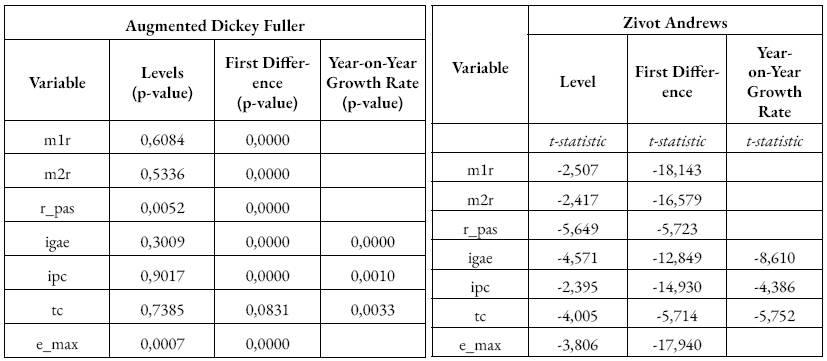
Table 6: Ardl Model - Short-Run Specification (Cp)
| Model CP 1 | Model CP 2 | Model CP 3 | Model CP 4 | Model CP 5 | Model CP 6 | |
|---|---|---|---|---|---|---|
| L.lm_2 | 0,972*** | 0,992*** | 0,991*** | 0,991*** | 0,812*** | 0,816*** |
| (0,05) | (0,00) | (0,00) | (0,00) | (0,05) | (0,05) | |
| L2.lm_2 | 0,189** | 0,175*** | 0,171*** | |||
| (0,07) | (0,05) | (0,05) | ||||
| L3.lm_2 | 0,012 | |||||
| (0,07) | ||||||
| L4.lm_2 | -0,174*** | |||||
| (0,05) | ||||||
| e_max | -0,006 | -0,099*** | -0,100*** | -0,098*** | -0,052* | -0,053* |
| (0,02) | (0,03) | (0,03) | (0,03) | (0,03) | (0,03) | |
| dummy_m2r | 0,002 | -0,006 | -0,010* | -0,010* | -0,014*** | -0,015*** |
| (0,00) | (0,00) | (0,01) | (0,01) | (0,01) | (0,01) | |
| d2005 | 0,039*** | 0,023* | 0,022* | 0,023* | 0,016 | 0,016 |
| (0,01) | (0,01) | (0,01) | (0,01) | (0,01) | (0,01) | |
| d2008 | -0,040*** | -0,046*** | -0,045*** | -0,045*** | -0,049*** | -0,049*** |
| (0,01) | (0,01) | (0,01) | (0,01) | (0,01) | (0,01) | |
| d2020 | 0,017 | 0,032** | 0,032** | 0,042** | 0,042*** | 0,034*** |
| (0,01) | (0,01) | (0,01) | (0,02) | (0,02) | (0,01) | |
| r_pas | -0,003*** | -0,004*** | -0,004*** | -0,004*** | -0,004*** | |
| (0,00) | (0,00) | (0,00) | (0,00) | (0,00) | ||
| t_ipc | -0,001 | -0,001 | -0,002*** | -0,002*** | ||
| (0,00) | (0,00) | (0,00) | (0,00) | |||
| t_igae | 0,0004 | 0,0003 | ||||
| (0,00) | (0,00) | |||||
| t_tc | -0,026*** | -0,026*** | ||||
| (0,00) | (0,00) | |||||
| L.t_tc | 0,025*** | 0,025*** | ||||
| (0,00) | (0,00) | |||||
| Constant | 0,01 | 0,062*** | 0,078*** | 0,076*** | 0,114*** | 0,115*** |
| (0,01) | (0,01) | (0,02) | (0,02) | (0,02) | (0,02) | |
| BIC | -1,627 | -1,663 | -1,659 | -1,654 | -1,684 | -1,689 |
| N | 354 | 354 | 354 | 354 | 354 | 354 |
Source: Own Elaboration
The cointegration test of the variables is presented in the appendix. The Pesaran, Shin, and Smith test shows the existence of cointegration, supporting the stability of the relationship between the model variables (Table 9).
The scale variable has been omitted, as in the demand model for hyperinflationary economies by Cagan [22], and as in Kamin and Ericsson [3]. Preliminary research has not found a significant role for GDP or IGAE in the specification of the models for M1 and M2, and their exclusion partially improves the fit of the models.
According to Table 7, the estimated parameters are significant and consistent with theoretical expectations. As part of the robustness strategy, the model was re-estimated using three alternative horizons for the exchange rate depreciation expectations variable: 12, 24 and 36 months (corresponding to the variables emax1, emax2 and e max3, respectively). The results show a remark- able stability in the coefficients associated with the main variables (rpas, tipc and ttc), both in magnitude and significance. Likewise, the coefficient of expectations maintains the theoretically expected sign (negative) in all three specifications, being statistically significant in all models. These findings suggest that the estimated relationship between depreciation expectations and real money demand is robust to the time horizon considered, validating the use of emax as a guide variable in the base model (Table 8).
Table 7: Ardl Model - Long Run Specification (Lp)
| Model LP 1 | Model LP 2 | Model LP 3 | Model LP 4 | Model LP 5 | Model LP 6 | |
|---|---|---|---|---|---|---|
| ADJ | ||||||
| L.lm_2 | -0,001 | -0,008*** | -0,009*** | -0,009*** | -0,014*** | -0,014*** |
| (0,00) | (0,00) | (0,00) | (0,00) | (0,00) | (0,00) | |
| LR | ||||||
| e_max | -6,053 | -12,870*** | -10,946*** | -10,632*** | -3,807* | -3,911* |
| (27,94) | (4,36) | (3,71) | (3,67) | (2,11) | (2,11) | |
| r_pas | -0,405*** | -0,401*** | -0,390*** | -0,291*** | -0,297*** | |
| (0,07) | (0,06) | (0,06) | (0,05) | (0,06) | ||
| t_ipc | -0,075 | -0,079 | -0,150*** | -0,149*** | ||
| (0,05) | (0,05) | (0,03) | (0,03) | |||
| t_igae | 0,038 | 0,021 | ||||
| (0,04) | (0,03) | |||||
| t_tc | -0,089* | -0,089* | ||||
| (0,05) | (0,05) | |||||
| R2 | 0,093 | 0,158 | 0,159 | 0,159 | 0,259 | 0,259 |
| β=0 | 0,050 | 20,380 | 19,330 | 14,590 | 29,190 | 36,280 |
| 0,829 | 0,000 | 0,000 | 0,000 | 0,000 | 0,000 | |
| BIC | -1.627 | -1.663 | -1.659 | -1.654 | -1.684 | -1.689 |
| N | 354 | 354 | 354 | 354 | 354 | 354 |
Source: Own Elaboration
Table 8: Ardl Model - Long Run Specification (Lp)
| Model LP 6.1 | Model LP 6.2 | Model LP 6.3 | |
|---|---|---|---|
| ADJ | |||
| L.lm_2 | -0,013*** | -0,014*** | -0,014*** |
| (0,00) | (0,00) | (0,00) | |
| LR | |||
| r_pas | -0,275*** | -0,297*** | -0,296*** |
| (0,05) | (0,06) | (0,06) | |
| t_ipc | -0,139*** | -0,145*** | -0,159*** |
| (0,03) | (0,03) | (0,03) | |
| t_tc | -0,103*** | -0,086* | -0,103*** |
| (0,05) | (0,05) | (0,05) | |
| e_max1 | -5,383* (3,02) | ||
| e_max | -3,911* (2,11) | ||
| e_max3 | -3,618** (1,70) | ||
| R2 | 0,259 | 0,259 | 0,269 |
| β=0 | 36,290 | 36,280 | 36,640 |
| BIC | -1,687 | -1,689 | -1,634 |
| N | 354 | 354 | 342 |
Source: Own Elaboration
Table 9: Kripfganz And Schneider (2020) Critical Valúes And Approximate P-Values
| Critical Values (F) | P-value (F) | |||
|---|---|---|---|---|
| Significance Level | I(0) | I(1) | I(0) | I(1) |
| 10% | 2,454 | 3,531 | 0,000 | 0,000 |
| 5% | 2,879 | 4,033 | 0,000 | 0,000 |
| 1% | 3,792 | 5,092 | 0,000 | 0,000 |
| Critical Values (t) | P-value (t) | |||
| Significance Level | I(0) | I(1) | I(0) | I(1) |
| 10% | -2,560 | -3,646 | 0,000 | 0,000 |
| 5% | -2,859 | -3,974 | 0,000 | 0,000 |
| 1% | -3,411 | -4,590 | 0,000 | 0,000 |
|
F-statistic: 13,525 t-statistic: -6,495 |
||||
| Decision Rule: Reject H0 if both F and t are more extreme than critical values for I(1). Do not reject H0 if either F or t are closer to zero than critical values for I(0). | ||||
| Decision | 10% | 5% | 1% | |
| Reject | Reject | Reject | ||
Source: Own Elaboration
Table 10: Breusch-Godfrey Lm Test For Autocorrelation
| Lags (p) | F | df | Prob > F |
|---|---|---|---|
| 1 | 1,521 | (1, 341) | 0,2183 |
| 2 | 0,948 | (2, 340) | 0,3887 |
| 3 | 0,649 | (3, 339) | 0,5840 |
| 4 | 0,555 | (4, 338) | 0,6958 |
Source: Own Elaboration
Source: Own Elaboration
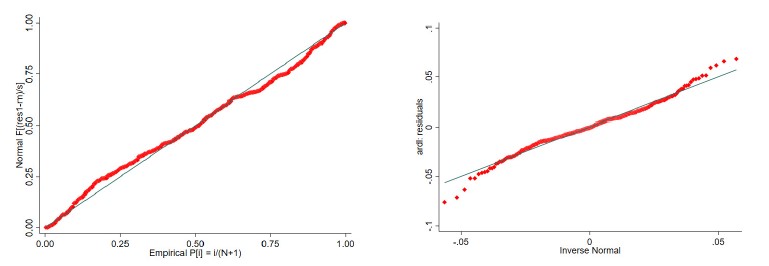
Figure 8: Standardized normal probability plot and Quantiles of residuals against quantiles of normal distribution.
5.1 Estimation of Dollar Demand
Once the coefficient \(\theta_4=\frac{\sum_{i=0}^q\rho_i}{1-\sum_{i=1}^p\beta_i}\) is calculated, which is estimated from the model and represents how agents react to expectations of devaluation, following Kamin and Ericsson [3], the difference between \(M_t^*\) \(M_t\) would represent the demand for dollars measured in bolivianos. This can be expressed as follows:
To proceed with estimating the dollars demanded by the public, it is assumed that the total demand for money consists of an observable component (national currency) and a non-observable component (dollars), as follows:
Using the two previous equations and performing the necessary operations, we obtain the value of the dollars demanded by the public in period, which can be expressed as follows:
Replacing
The estimation Qt would serve as a proxy for the amount of dollars demanded by the public as a store of value.
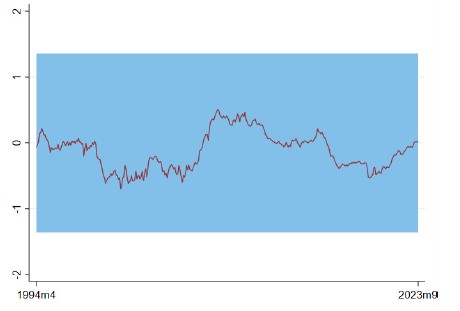
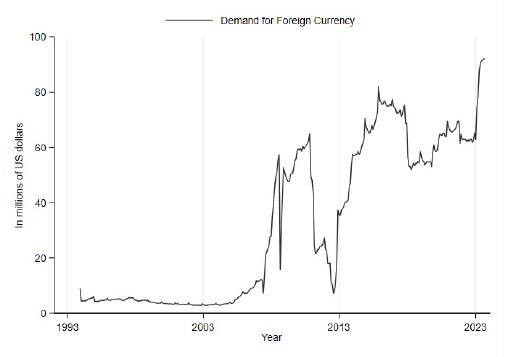
As can be seen in Figure 10, the estimation of the demand for dollars following the proposed methodology manages to capture the specific increases in electoral periods, as well as the demand in foreign currency due to devaluation expectations, specifically as of September 2023, $us92 million were demanded and accumulated from January to September, $us760 million.
5.2. Applying dynamic ARDL simulations
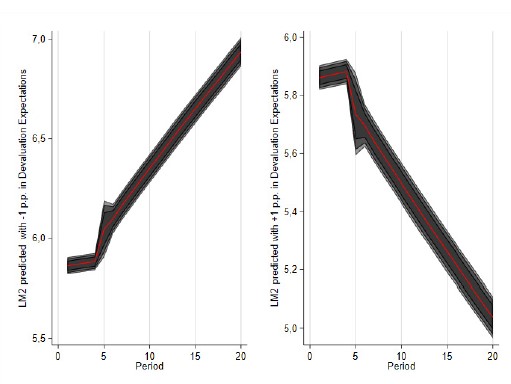
The flexibility of the ARDL model allows us to analyze the dynamic impact of a structural shock in an independent variable, whether positive (+) or negative (-) on the dependent variable, by dynamically simulating the effects of a counterfactual change in a weakly exogenous regressor at a point in time, using stochastic simulation techniques. The dynamic ARDL simulations performed are based on a 1 percentage point (+/-) contribution in the devaluation expectations, such a counterfactual shows how the logarithm of real balances can be affected. These dynamic simulation approaches are increasingly popular for showing the substantive results of time series models, whose coefficients often have non-intuitive or “hidden” interpretations Sarkodie and Owusu [23], Breunig and Busemeyer [27], Williams and Whitten [28], Gandrud et al. [29] and Philips et al. [30].
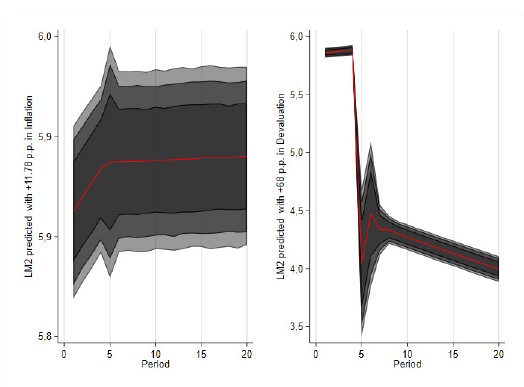
To account for the effect of a decrease or increase in devaluation expectations on the logarithm of the real balance of the M2 aggregate, we evaluated counterfactual shocks through dynamic ARDL simulations. The graph showing the dynamic ARDL simulations6 reveals that a -/+ 1 p.p. shock in devaluation expectations can affect the real balance of the M2 aggregate in the first period, but growth accelerates from the fifth period onwards. It also shows that the change in devaluation expectations will have a lasting impact (see Figure 12). As a robustness check, we analyzed the dynamic response of the proposed real money demand to two conceptually related exogenous shocks, an 11,78 percentage point increase in inflation and a 68 percentage point increase in the nominal exchange rate devaluation rate. Although both variables represent pressures from different channels, the results show a significant asymmetry in the responses: while the inflationary shock does not generate statistically significant variations in the real monetary aggregate, stabilizing it, the exchange rate shock induces a pronounced and persistent contraction in the demand for money. This difference suggests that economic agents internalize more acutely the risks associated with exchange rate instability than those associated with moderate price level increases (see figure 11).
Source: Own Elaboration
Figure 11: Counterfactual shock in devaluation expectations using dynamic ARDL simulations
Source: Own Elaboration
Note: p.p.: percentage point.
Figure 12: Representation of the counterfactual shocks using dynamic ARDL simulations
The red line is the LM2 predicted by -/+1 p.p. shock to devaluation expectations in the proposed econometric model; the gray areas (dark, medium dark and light) denote 75, 90 and 95% confidence interval.
6. Conclusions
This paper presents a rigorous analysis of the demand for dollars in Bolivia, framed within the context of economic instability, devaluation expectations, and a lack of confidence in the national currency. Using an ARDL model, the study effectively quantifies the dynamics of dollar demand and highlights its driving factors, such as inflation, real interest rates, and uncertainty. These findings reinforce theoretical insights into currency substitution and store-of-value motives during periods of heightened economic risk.
The results demonstrate that devaluation expectations and inflation significantly drive the public’s preference for holding dollars over the Boliviano. Quantitatively, the model estimates that dollar demand rose to approximately $us760 million in 2023. This underscores the critical relationship between macroeconomic stability and the public’s trust in the local currency, offering valuable implications for monetary policy design and the importance of addressing external vulnerabilities.
These findings support the study’s hypothesis, which posits that the public has reconstituted dollar holdings in anticipation of a foreign currency shortage. To this end, the Kamin and Ericsson [3] methodology was applied for the period between 1993 and 2023, estimating that the demand for dollars as a store of value increased significantly over the past year. In September 2023, this trend was a total of $us760 million.
This phenomenon has altered the preferences of economic agents, who have increasingly adopted the dollar not only as a medium of exchange but also as a reserve asset. The document introduces the concept of currency co-existence, which creates an environment where dollar demand becomes a barometer of confidence in the country’s economic stability and monetary policy. The ability of citizens to access dollars has emerged as a critical factor in ensuring a more secure and predictable economic environment.
Policy recommendations focus on bolstering confidence in the Boliviano by maintaining low inflation through sound fiscal and monetary policies and ensuring transparency in central bank operations. While a fixed exchange rate offers stability, a gradual shift to a flexible regime can help absorb external shocks and manage inflation expectations. Reducing uncertainty through structural reforms, political stability, and clear communication is crucial. Promoting financial bolivianization with competitive returns on Boliviano-denominated savings and investments can reduce dollar dependence. Diversifying foreign exchange inflows through enhanced non-traditional exports, stronger trade relations, and formalized remittance channels is essential for improving currency availability and economic stability.
In the case of Bolivia, the lever with the highest return is anchoring exchange rate expectations. The BCB must strengthen forward guidance on the exchange rate regime, establish clear and predictable rules for providing foreign currency liquidity, and execute transparent micro-interventions that mitigate peaks in precautionary demand. At the same time, making instruments in the national currency (bolivianos) competitive by maintaining non-negative real deposit rates reduces the incentive to dollarize and favors substitution toward MN, in line with the sign of the opportunity cost estimated by the ARDL in the long term.
Future research should explore micro-level data on households and firms, compare dollar demand across Latin American economies, and include global factors like interest rates and commodity shocks. Investigating digital currencies as substitutes, using DSGE models for policy impacts, and incorporating behavioral insights on currency preferences during uncertainty would enhance understanding of dollarization dynamics.
In conclusion, this study provides a comprehensive and valuable analysis of the demand for foreign currency in Bolivia through a value storage lens. It offers significant insights into the underlying dynamics of dollarization while presenting a robust theoretical and empirical framework. These contributions not only enhance our understanding of currency substitution but also serve as a critical foundation for future research and the development of more effective economic policies.

